BUSINESS
Jefferson Signals an October Pause After September’s Hike
Vice Chair Jefferson said the Fed can wait after bond yields jumped, and a 29,000-job print then sank remaining October hike odds.

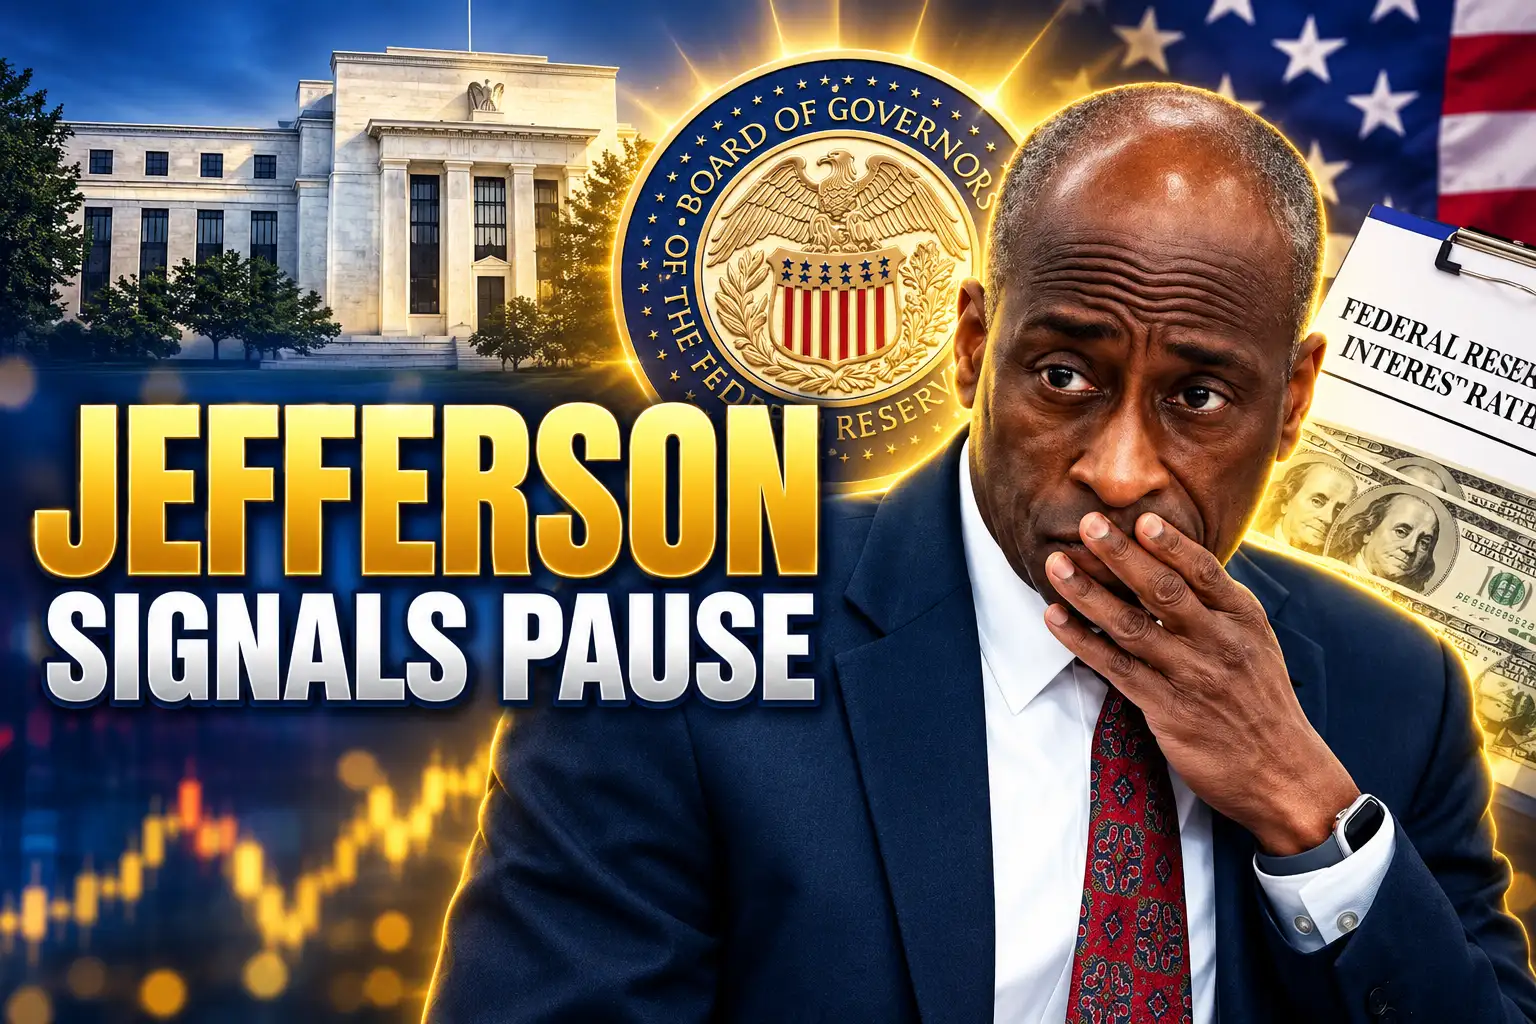
Federal Reserve Vice Chair Philip Jefferson said on October 1 that officials may need more time before raising rates again. The comment came two weeks after the first hike since 2023, and a day before employers added only 29,000 jobs.
Traders had spent late September pricing a second move for the October 27 and 28 meeting. They are not doing that now. Long-term yields had already jumped after the September rise, which is the tightening the skip now leans on.
A Patience Signal From Charlottesville
Jefferson spoke at the Darden School of Business in Charlottesville, a homecoming for the UVA Ph.D. He backed last month’s increase. He also declined to treat the next meeting as automatic.
The official Fed account posted his remarks at the University of Virginia as he delivered them.
Speech by Vice Chair Jefferson on the U.S. economy and monetary policy @DardenMBA: https://t.co/2GLxgesNqb
Watch live: https://t.co/QdJFQmwV6Y
Learn more about Vice Chair Jefferson: https://t.co/oUzpfyg7jd— Federal Reserve (@federalreserve) October 1, 2026
As we look ahead, my view is that any future adjustments in policy should be determined by carefully examining trends in the data, the evolving outlook, and the balance of risks. Since our September meeting, yields across the term structure have increased further, a sign that investors are reassessing the evolving macroeconomic landscape. My colleagues and I will need to come to our own judgment, which may take more time.
Philip N. Jefferson, Vice Chair, Board of Governors of the Federal Reserve System, Darden School of Business
He still described a hard inflation problem. Prices have sat above the 2% goal for more than five years, and he sees upside risks even as risks to jobs and growth look “roughly balanced.” Energy, an AI buildout, and shifts in trade policy are hitting at once, he said, and the committee cannot treat those shocks one at a time.
Growth in the first half ran at a 2.4% pace, in line with the prior two years. He called the August jobless rate of 4.1% close to maximum employment. His base case is that inflation stays high in the near term, then eases as energy and other price shocks fade. That is a hold speech dressed in hawkish facts, and markets heard the hold.
What the September Rate Rise Set in Motion
The FOMC voted 12-0 on September 16 to raise the funds rate by a quarter point to 3.75% to 4%. It was the first increase since 2023 and the first under Chair Kevin Warsh. The statement said activity was expanding at a solid pace, inflation remained elevated, and the move would support a timelier return to 2%.
Jefferson called that vote “an important step to ensure longer-term inflation expectations remain well anchored.” Short-term survey measures of expected inflation are still high, he said, while most longer-term measures have stayed consistent with 2%. The fear he named is that households and firms stop believing the return to target if actual inflation stays high.
That framing left a second hike on the table. It did not lock in October. Between the September 16 vote and Jefferson’s speech, the 10-year Treasury yield had already made a statement of its own. On September 23 it rose 0.147 percentage point to 5.113%, the highest close since July 2007. Jefferson pointed at that backup in yields as evidence investors were repricing the outlook, and as a reason the Fed could take more time to form its own view.
Evercore ISI read the Charlottesville text as confirmation that a back-to-back hike in October is not the base case. The September rise still stands. The path after it is what broke.
Williams Took the Urgency out of October
New York Fed President John C. Williams got there first. In Buffalo on September 29 he said that with the September action there is no need for urgency after September, and that officials have time to gather more information.
“If the economy evolves in a manner broadly consistent with my forecast, one further upward adjustment of the federal funds target range may be appropriate late this year to support a timelier return of inflation to target,” he said. Then he added that this is his forecast, and that time and the full run of data will tell.
Williams is a permanent voter and vice chair of the rate-setting committee. He still wants another increase if the outlook holds. He does not want it on a hurry-up calendar. That pairing, one more hike and no rush, is what pulled October out of the priced path and left December as the live date on the 2026 calendar, with the December 8 and 9 meeting the remaining session after October.
Chair Warsh has stepped back from the old habit of spelling out the next move in advance. When the chair will not supply that map, a vice chair and the New York president talking in public become the map. The burst of speeches is the guidance the committee says it no longer gives.
A 29,000-Job Print Changes the October Math
Jefferson was still working off August labor data when he spoke. The September report arrived at 8:30 a.m. Eastern on October 2. The Bureau of Labor Statistics recorded nonfarm payroll employment of 29,000, and the unemployment rate ticked up to 4.2% from 4.1%.
Economists tracked by FactSet had expected about 90,000 jobs. Average hourly earnings rose 5 cents, or 0.1%, to $37.81, and are up 3.0% over the year, below the 3.4% pace of headline consumer prices. The average workweek held at 34.4 hours.
PAYROLLS AND UNEMPLOYMENT, REVISED
| Metric | July 2026 | August 2026 | September 2026 |
|---|---|---|---|
| Payroll change | -10,000 | +133,000 | +29,000 |
| Unemployment rate | 4.1% | 4.1% | 4.2% |
July was revised from a gain of 21,000 to a loss of 10,000. August was revised from 162,000 to 133,000. The two months together are 60,000 weaker than first reported. Over the prior 12 months, payrolls had risen by an average of 45,000 a month. September landed well below that run rate.
SEPTEMBER PAYROLLS BY INDUSTRY
- Health care: Up 17,000, against a 12-month average of 33,000.
- Construction: Up 11,000, in line with its recent monthly pace.
- Manufacturing: Up 9,000, and up 72,000 since a low in December 2025.
- Information: Down 10,000.
- Financial activities: Down 7,000, and down 129,000 since a peak in May 2025.
- Professional and business services: Down 9,000.
The household survey was not a collapse. Labor-force participation rose to 61.8%, and the employment-population ratio ticked up to 59.2%. Layoffs in Jefferson’s telling had remained low. A 29,000 print with downward revisions is still a soft establishment survey, and it arrived after two of the committee’s most senior officials had already taken the urgency out of October.
September consumer prices are due on October 14. That print, not this jobs report, is the last major inflation reading before the meeting. A hot CPI could still reprice December. It would have to work much harder to revive a hike in three weeks.
Kashkari Still Sees Hikes Into Next Year
Minneapolis Fed President Neel Kashkari did not join the stand-down. In an October 1 interview he said he was “open-minded” on how to proceed and did not have “a strong view” on whether the next increase should come at the October 27 and 28 meeting. He still expects more tightening into 2027.
Kashkari voted for the September rise. The projections he filed for that meeting called for one more quarter point this year and another in 2027. He said that if the economy stays “incredibly resilient” and inflation is stickier than he thinks, policy may need to go higher than he is penciling in now.
Goldman Sachs moved the other way after the August price report. The firm pushed its second hike to December and said there is a strong chance the committee will conclude that further increases are unnecessary. Vice Chairman Rob Kaplan, a former Dallas Fed president, had already sketched a similar path in late September: skip October unless the data force a move, look again in December, and treat a funds rate around 4% to 4.25% as close to neutral.
WHERE OFFICIALS AND FORECASTERS SPLIT
- Jefferson and Williams: No rush in October. One more increase may still be warranted late in 2026 if the forecast holds.
- Kashkari: No strong view on October, but more hikes likely into 2027 if inflation stays high and demand holds.
- Goldman Sachs: Second hike delayed to December, with a strong chance the committee stops after that.
That split is why a skipped October meeting would not settle the year. Williams still has “late this year” in his forecast. Kashkari has 2027. Goldman is the shop willing to say the September rise might be the last. The jobs report helps the skip camp. It does not retire the inflation argument, and Jefferson did not retire it either.
How Fast the October Hike Odds Fell
CME FedWatch, which reads 30-day fed funds futures, put a 25-basis-point October hike at 68.6% a week before Jefferson spoke. After the August price report on September 30, that probability was 38.2%, with a hold at 61.8%. After Jefferson on October 1 it was 24.9%.
The September jobs miss then pushed prediction markets further into a hold. On October 2, after the payrolls release, Polymarket priced no change at 82.5% and a quarter-point hike at 15.5%. Kalshi was 83% for a hold and 16% for a 25-basis-point rise.
OCTOBER 2 HOLD VERSUS HIKE
| Market | Hold | 25 bp hike |
|---|---|---|
| Polymarket | 82.5% | 15.5% |
| Kalshi | 83% | 16% |
Those two books now agree within a point. A week earlier they were pricing the opposite outcome. The collapse is the story in the futures pit and on the crypto-linked prediction markets that have become a parallel Fed funds tape.
A hold in October is not a bet that rates are finished. Williams still sees one more increase this year if his forecast is right. The priced path has become skip-then-maybe, not peak-and-done. CPI on October 14 sits on that second leg. So does any fresh jump in energy prices, which Jefferson flagged as the main driver of the recent pickup in headline inflation.
Extra Tightening From the Treasury Market
The policy rate moved a quarter point on September 16. Market rates moved more. Jefferson named that backup across the yield curve as a reason to wait. The Fed can hold at 3.75% to 4% and still argue that financial conditions tightened, because the long end did part of the work a second hike would have done.
THE WEEK THE OCTOBER BET UNWOUND
- September 16, 2026: The FOMC raises the funds rate to 3.75% to 4% on a 12-0 vote, the first hike since 2023.
- September 23, 2026: The 10-year yield rises 0.147 point to 5.113%, the highest since July 2007.
- September 29, 2026: Williams in Buffalo says there is no need for urgency and points to one more possible increase late in the year.
- September 30, 2026: The PCE price index rose 3.4 percent from a year earlier, with core up 0.2% on the month and 3.0% on the year, both below what economists had built in.
- October 1, 2026: Jefferson says the next adjustment may take more time. CME FedWatch’s October hike odds fall to 24.9%.
- October 2, 2026: Payrolls rise 29,000. Polymarket’s hold price moves to 82.5%.
Personal spending still jumped 0.9% in August, and real spending rose 0.6%. Income was up only 0.2%, and the saving rate was 4.1%. Demand has not rolled over. That is Kashkari’s case for more hikes later. It is also why Jefferson keeps upside risks on inflation even while he waits.
Financial activities payrolls are down 129,000 since May 2025, with most of the loss in insurance. Credit can tighten without another quarter point on the funds rate, through wider spreads, harder refinancing, and fewer new deals. Officials who sound worried about prices and still refuse to hurry October are acting as if some of that channel is already open.
The October 27 and 28 meeting is now set up as a hold unless the next inflation report is a blowout. December is the date that still carries a hike. Jefferson did not take that date away. He took the one in front of it, and Friday’s jobs number made the choice look cheaper to defend.
Disclaimer: This article is news reporting and analysis of Federal Reserve communications, labor and inflation data, and market-implied odds. It is for information only and is not investment, trading, or policy advice. It does not recommend buying or selling securities, futures, prediction-market contracts, or cryptocurrencies, and it does not tell readers how to position around FOMC meetings. Consult a qualified financial adviser or licensed investment professional before acting on rate-path or market views. Figures and probabilities reflect the cited official releases and market readings as of the dates named above and will change with new data and new speeches.

TCS Opens Q2 as Mid-Cap IT Keeps the Growth

Bitcoin’s Jobs Rally Fails While December Hike Odds Hold

The Heat Turn a Bucks Rematch Into Vice City Night

The G7 Opens Diesel Tanks While Carriers Head East

Kia Bets Fortuner Money on a Made-in-India Sorento

Volkswagen Sells the Osnabruck Plant to Clear a Board Fight

Tata Motors’ Iveco Tender Opens as Holders Still Decide

Saksham Gaur Finds He Is His Own Company’s Client

Onimusha Way of the Sword Preload Hits a Windows 11 Wall

The Frame Pro’s $1,200 Labor Day Cut Needs a Soundbar
-
 AUTO4 weeks ago
Volkswagen Sells the Osnabruck Plant to Clear a Board Fight
-
 AUTO1 month ago
Tata Motors’ Iveco Tender Opens as Holders Still Decide
-
 BUSINESS1 month ago
Saksham Gaur Finds He Is His Own Company’s Client
-
 GAMING1 month ago
Onimusha Way of the Sword Preload Hits a Windows 11 Wall
-
 NEWS4 weeks ago
The Frame Pro’s $1,200 Labor Day Cut Needs a Soundbar
-
 BUSINESS1 month ago
The Rs 4.66 Lakh Crore IPO Queue Is Mostly Paper
-
 BUSINESS1 month ago
Hyderabad 22-Carat Gold Jumps After a False Bargain
-
 NEWS1 month ago
Apple’s Foldable iPhone Hinges on Samsung Display Supply