BUSINESS
Patrick Witt Backs a Treasury Switch on Stablecoin Yields
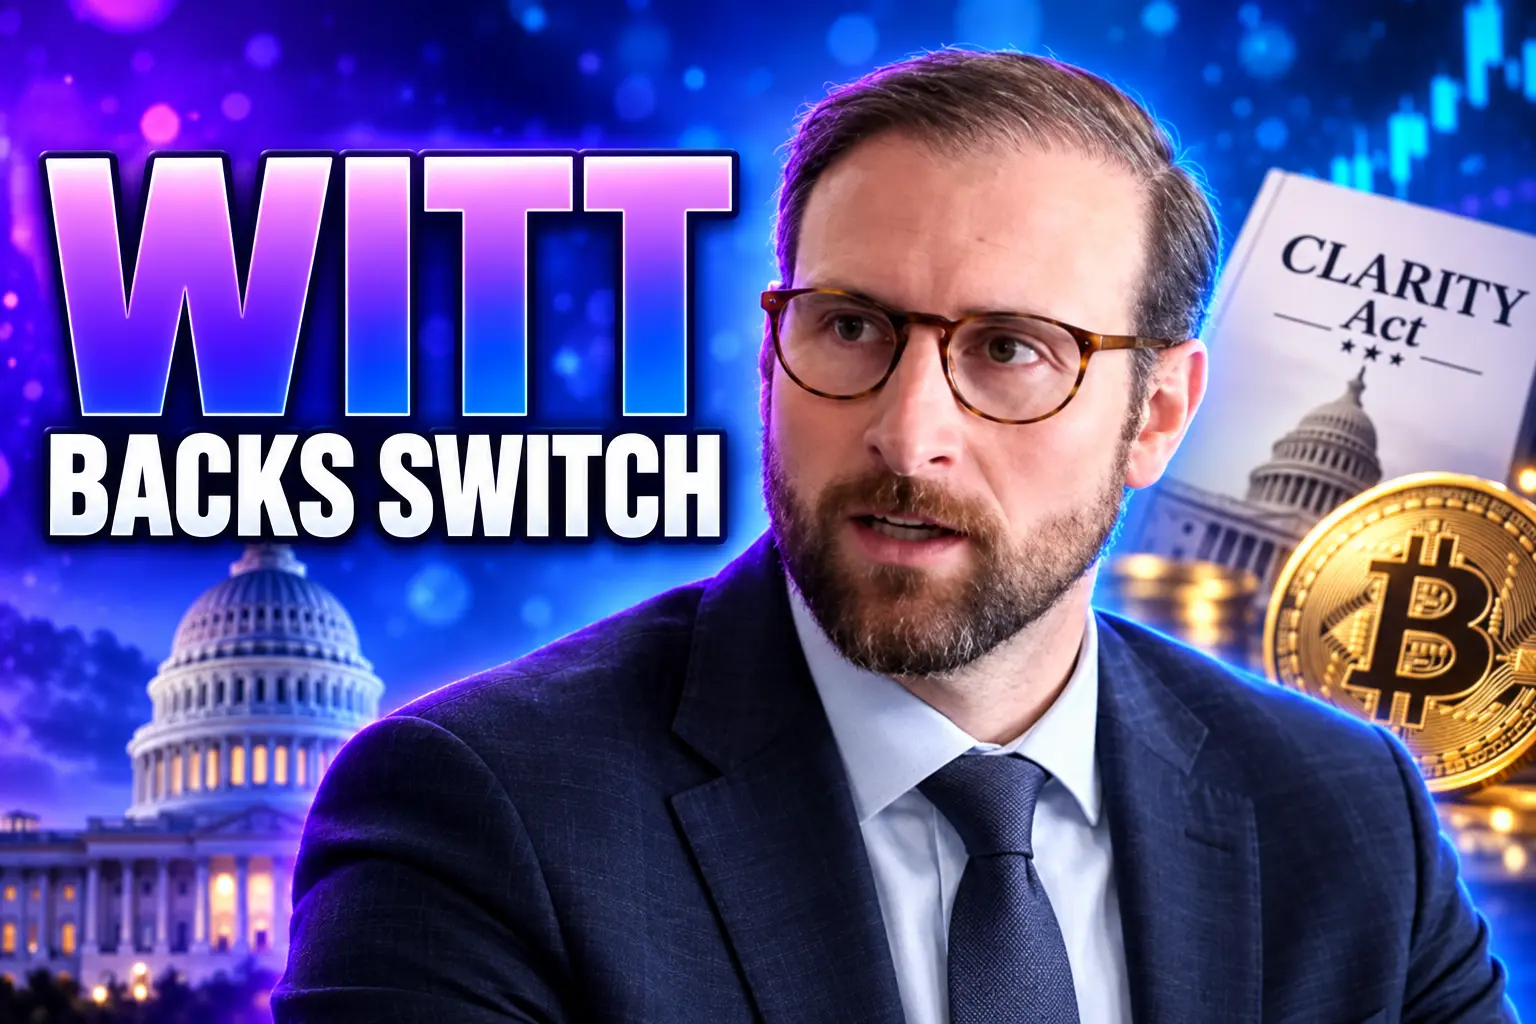
Patrick Witt backed a delayed Treasury brake on CLARITY Act stablecoin rewards while calling bank deposit flight a myth ahead of the Senate vote.

Patrick Witt, executive director of the President’s Council of Advisors for Digital Assets, backed new CLARITY Act limits on stablecoin rewards on Sept. 14. He also called the banks’ deposit-flight warning a myth, saying balances are still rising.
The 635-page Senate draft he is selling still hands Treasury Secretary Scott Bessent an 18-month switch that fires only after community banks have already lost deposits. The Senate is set to hold a cloture vote on H.R. 3633 at 2:15 p.m. Eastern on Sept. 15. That roll call needs 60 votes and would only open debate.
Patrick Witt Backs a Switch He Calls Unnecessary
Witt wrote on X that crypto firms have paid rewards on stablecoins for years, so the feared run on bank deposits should already be visible in the numbers. He said it is not.
If the deposit flight myth were true, it would have already happened.
Patrick Witt, Executive Director, President’s Council of Advisors for Digital Assets, on X
He still endorsed Section 404, which restricts rewards that mimic interest on bank deposits, and the new Treasury circuit breaker sitting beside it. At a Solana Policy Institute summit in Washington the same day, he called the draft the “best and final offer” and said a 60-vote outcome would be “a political calculation, not a policy calculation.”
He also said Republicans had accepted 95% of Democratic negotiators’ asks, a figure that is his, not a Democratic whip count. The posture is the tell. The White House’s crypto adviser is arguing the banks’ core fear has not shown up in the data, then asking the Senate to write that fear into statute as a standby power for Treasury.
The Rewards Loophole GENIUS Left Behind
The fight is not about whether issuers can staple a savings rate onto a dollar token. Congress already closed that door.
The GENIUS Act, signed in July 2025 as P.L. 119-27, tells a permitted payment stablecoin issuer it may not pay the holder any form of interest or yield solely for holding, using, or keeping the coin. A Congressional Research Service brief on issuers paying interest or yield walks through why that ban does not settle the market that actually exists.
Most retail users do not buy the coin from the issuer. They hold it at an exchange. Circle, which issues USDC, passes a share of reserve income to Coinbase in proportion to the USDC sitting on that platform, and the exchange can pay the customer. GENIUS never defined “holder” in a way that clearly catches that three-party loop, so the payment can be labeled a reward rather than interest.
That is the product the banking lobby is trying to kill, and it is the product that survives if CLARITY dies. Witt put the trap in plain language months ago, when he wrote that no compromise on CLARITY means no new limits on intermediaries, which, if the banks’ own warning is right, would be the worse outcome for deposits.
Can someone please explain to me the logic here?
No compromise on CLARITY means no restrictions on intermediaries offering stablecoin rewards. If you believe the banks’ argument about deposit flight, this would be catastrophic.
Feels like I’m watching an arsonist threaten to… https://t.co/NsVjhJCqx7
— Patrick Witt (@patrickjwitt) March 7, 2026
What Section 404 Would Ban
The Senate text tries to split idle balances from payments. Covered digital-asset platforms and their affiliates would be barred from paying U.S. customers interest or yield just for holding payment stablecoins. Rewards tied to activity or transactions could remain, subject to later rulemaking. Platforms could not market the coins as bank deposits, investment products, government-backed products, or FDIC-insured products.
Bank groups say the line is easy to walk around. They want language struck that would still let an otherwise allowed reward vary with how many coins a customer holds and how long those coins sit. Duration, balance, and tenure are, they note, how interest is usually figured.
THE YIELD RULES IN PLAY
| Rule | Who it binds | What it blocks | What it still allows |
|---|---|---|---|
| GENIUS Act Section 4 | Permitted payment stablecoin issuers | Interest or yield paid solely for holding, using, or keeping the coin | Exchange-paid rewards in the three-party model |
| CLARITY Section 404 | Covered platforms and affiliates serving U.S. customers | Interest or yield paid solely for holding payment stablecoins; deposit-like marketing | Activity- or transaction-based rewards, pending rules |
| Treasury circuit breaker | Treasury, for 18 months after enactment | Further reward curbs if the secretary finds substantial community-bank deposit flight | No extra limit unless that finding is made in writing |
| Bank trades’ ask | Congress, in the statute itself | Interest-like rewards up front, including those tied to balance, duration, or tenure | A sharper payments-versus-savings split, with no wait for losses |
The table is the whole argument in four rows. GENIUS stopped the issuer. Section 404 tries to stop the platform from acting like a savings account. The breaker waits for blood on the floor. The banks want the ban written before anyone leaves.
Eight Banking Groups Say the Breaker Fires Too Late
On Sept. 14, eight trades wrote Senate Majority Leader John Thune and Democratic Leader Chuck Schumer. The signers were the American Bankers Association, the Association of Military Banks of America, the Bank Policy Institute, the Consumer Bankers Association, the Financial Services Forum, the Independent Community Bankers of America, the Mid-Size Bank Coalition of America, and the National Bankers Association.
They say they want a durable digital-asset rulebook. They also say payment stablecoins were built as payment tools, and that yield-like incentives would let those coins compete with deposits that fund home loans, farm credit, and small-business books, especially at community and mission-driven banks.
THE BANK LETTER’S DEMANDS
- Close the evasion path: Tighten the ban so interest-like payments on balances cannot be dressed up as activity rewards.
- Kill tenure math: Strike the clause that lets a permitted reward depend on how large a balance is and how long it is held.
- Do not wait for losses: Put the prohibition in the statute instead of handing Treasury a switch that trips after deposits have already left.
The letter supports a payments-versus-savings split in principle, then says the current drafting leaves holes. On the new backstop, the groups wrote that a circuit breaker is not a safeguard if it activates only after substantial deposit flight has already occurred.
Four days earlier, all 77 state bankers associations joined the ABA and the ICBA in a separate ask aimed at Section 10404, the same stablecoin-rewards title. That earlier letter said payment stablecoins should stay transactional tools, not store-of-value stand-ins for deposits, and that communities cannot afford the risk if the line stays fuzzy.
Community Bank Deposits Keep Climbing Anyway
Witt’s empirical claim is not hard to check. The Federal Reserve’s H.8 series puts deposits at all commercial banks at $19.54 trillion in August 2026, or $19,539.5747 billion, seasonally adjusted. That stock is the industry-wide number, not the community-bank book.
The FDIC’s second-quarter 2026 profile is the community series. It found that community banks reported deposit growth even as the rewards fight got louder. Domestic deposits at those banks were $2.3 trillion, up 0.4% or $9.2 billion from the prior quarter and up 4.6% or $103.2 billion from a year earlier. Community-bank assets were $2.8 trillion. Those firms are 90% of the 4,238 FDIC-insured commercial banks and savings institutions in the quarter.
DEPOSIT FIGURES IN 2026
- Industry stock: Commercial-bank deposits were $19.54 trillion in August, per the Fed’s H.8 series on FRED.
- Community stock: Community-bank domestic deposits were $2.3 trillion in the second quarter, per the FDIC.
- Community pace: That community book was up $103.2 billion, or 4.6%, from a year earlier.
- Cloture bar: Republicans hold 53 Senate seats, so a united conference still needs 7 Democratic or independent votes to reach 60.
The banking case has always been about the next leg, not the last print. The CRS brief cites a Treasury advisory model that treats a $6.6 trillion pool of U.S. transactional deposits as exposed if stablecoins become a closer substitute for checking. Citigroup research cited in the same brief puts stablecoins at $0.5 trillion to $3.7 trillion by 2030 and deposit displacement at $182 billion to $908 billion. A separate study it flags puts the possible hit to bank lending between $65 billion and $1.26 trillion.
Those are forecasts, not Q2 call reports. They also assume yield makes the coins more like a place to park cash. Section 404 is an attempt to keep that from becoming the default, without waiting to see whether the forecasts were right.
How the Treasury Kill Switch Would Work
Sens. Cynthia Lummis of Wyoming, John Boozman of Arkansas, and Tim Scott of South Carolina released the substitute on Sept. 14 and said it includes 126 substantive changes requested by Democrats. Lummis said the draft gives the secretary of the Treasury new authority to prevent deposit flight tied to payment stablecoins, framed as a circuit breaker for community banks and the farmers and small businesses that borrow from them.
After a year of intense daily bipartisan negotiations, this bill is ready. Here is the final text. President Trump voluntarily agreed to new ethics provisions holding every federally elected official, judge, and their spouses to some of the toughest ethics restrictions in U.S.…
— Senator Cynthia Lummis (@SenLummis) September 14, 2026
The mechanics are narrower than the press-release slogan. If the Treasury secretary determines in writing that substantial deposit flight is underway at community banks, the department would be directed to write rules that further restrict rewards available to payment-stablecoin holders. That authority would expire 18 months after enactment. It is a sunset, not a permanent new office.
Bessent has already said he would use it. He wrote that the final draft gives him added room if facts on the ground change and start to hurt community banks, and that he wants both the new technology and those banks contributing to growth.
If stablecoins cause harm to community banks, I will not hesitate to use these tools to ensure they remain fully protected.
Scott Bessent, Treasury Secretary, on X
Scott, who ran the Banking Committee title, said the same draft “gives the Treasury Secretary the tools to protect community banks, farmers, and rural Americans.” The banks’ reply is that a tool timed to losses is a mop, not a lock. Crypto desks that still pay holders for idle USDC have the opposite problem: even a mop in Bessent’s closet is a price-setting risk, because a written finding could cut the reward mid-product.
The delayed fuse is the second-order fact. Witt can keep saying the boogeyman has not arrived. The statute he is backing still treats that boogeyman as worth an emergency rule, then takes the emergency away after 18 months whether or not the deposits came back.
Sixty Votes Would Only Open the Floor
Cloture on the motion to proceed is not passage. The Senate Republican Cloakroom listed a roll call at 2:15 p.m. on Sept. 15 on H.R. 3633. If cloture is invoked, sponsors plan to offer the new text as an amendment in the nature of a substitute. Hours of debate, possible amendments, a separate passage vote, and a House vote on that Senate language would still sit ahead of a signing statement.
Votes scheduled: At 11:15am, on Tuesday, September 15th, the Senate will proceed to a roll call vote on confirmation of Executive Calendar #902, Matthew R. Byrne to be United States District Judge for the Southern District of Ohio.
At 2:15pm, the Senate will proceed to a roll…— Senate Cloakroom (@SenateCloakroom) September 14, 2026
THE PATH TO THE FLOOR
- July 2025: The House passes H.R. 3633, 294-134. GENIUS is signed the same month and bans issuer-paid stablecoin yield.
- May 2026: The Senate Banking Committee advances the Clarity title 15-9.
- Sept. 10, 2026: All 77 state bankers associations, with the ABA and ICBA, ask for a harder Section 10404 ban.
- Sept. 14, 2026: Lummis, Boozman, and Scott release the 635-page substitute; eight national trades send the circuit-breaker letter; Witt backs Section 404 and calls deposit flight a myth.
- Sept. 15, 2026: Cloture on the motion to proceed is scheduled for 2:15 p.m. Eastern and needs 60 votes.
The arithmetic is thin. Fifty-three Republican seats leave no spare room if the conference splits. Sen. John Cornyn of Texas told reporters on Sept. 14 that he was still considering how to vote and pointed to concerns from law enforcement groups and banks. Lummis, for her part, said a no vote means opposing the ethics package, handing digital-asset leadership to foreign competitors, and leaving U.S. customers with no statutory market protections. “Democrats got what they wanted; now they need to take yes for an answer,” she said.
The ethics title is the other half of the substitute, with state attorneys general given a role enforcing limits on officials who issue, sponsor, or hold large digital-asset stakes. That fight is real, and it may decide the 60. It does not change what Section 404 does to a USDC rewards balance if the bill ever becomes law.
If cloture fails, the GENIUS issuer ban stays and the exchange channel stays with it. That is the outcome bank trades have spent a year calling a threat to local lending. It is also the outcome they risk by treating a delayed Treasury switch as worse than no bill. Witt has been pointing at that contradiction since March. The Sept. 15 vote is where the Senate either writes the contradiction into law or leaves the loophole he described sitting where GENIUS left it.
Disclaimer: This article is news reporting and analysis of pending U.S. legislation and related public data. It is informational only and is not investment, legal, tax, or banking advice, and it is not a recommendation to buy, sell, or hold any digital asset, stablecoin, deposit product, or security. Readers who may be affected by stablecoin rewards rules, bank-deposit products, or the CLARITY Act should consult a qualified attorney, licensed financial adviser, or accountant before acting. Bill text, vote schedules, deposit figures, and product terms are those published by the sources named here as of Sept. 15, 2026, and can change with further Senate action, agency rulemaking, or later data releases.

TCS Opens Q2 as Mid-Cap IT Keeps the Growth

The Heat Turn a Bucks Rematch Into Vice City Night

The G7 Opens Diesel Tanks While Carriers Head East

Kia Bets Fortuner Money on a Made-in-India Sorento

Citi’s $240 MSTR Target Still Prices a Dilution Cut

Volkswagen Sells the Osnabruck Plant to Clear a Board Fight

Saksham Gaur Finds He Is His Own Company’s Client

Tata Motors’ Iveco Tender Opens as Holders Still Decide

Onimusha Way of the Sword Preload Hits a Windows 11 Wall

The Rs 4.66 Lakh Crore IPO Queue Is Mostly Paper
-
 AUTO4 weeks ago
Volkswagen Sells the Osnabruck Plant to Clear a Board Fight
-
 AUTO4 weeks ago
Tata Motors’ Iveco Tender Opens as Holders Still Decide
-
 BUSINESS4 weeks ago
Saksham Gaur Finds He Is His Own Company’s Client
-
 GAMING1 month ago
Onimusha Way of the Sword Preload Hits a Windows 11 Wall
-
 BUSINESS4 weeks ago
The Rs 4.66 Lakh Crore IPO Queue Is Mostly Paper
-
 NEWS1 month ago
Apple’s Foldable iPhone Hinges on Samsung Display Supply
-
 BUSINESS4 weeks ago
Hyderabad 22-Carat Gold Jumps After a False Bargain
-
 AUTO4 weeks ago
Simple Wave Chases Range as Ather Konarc Cuts Price